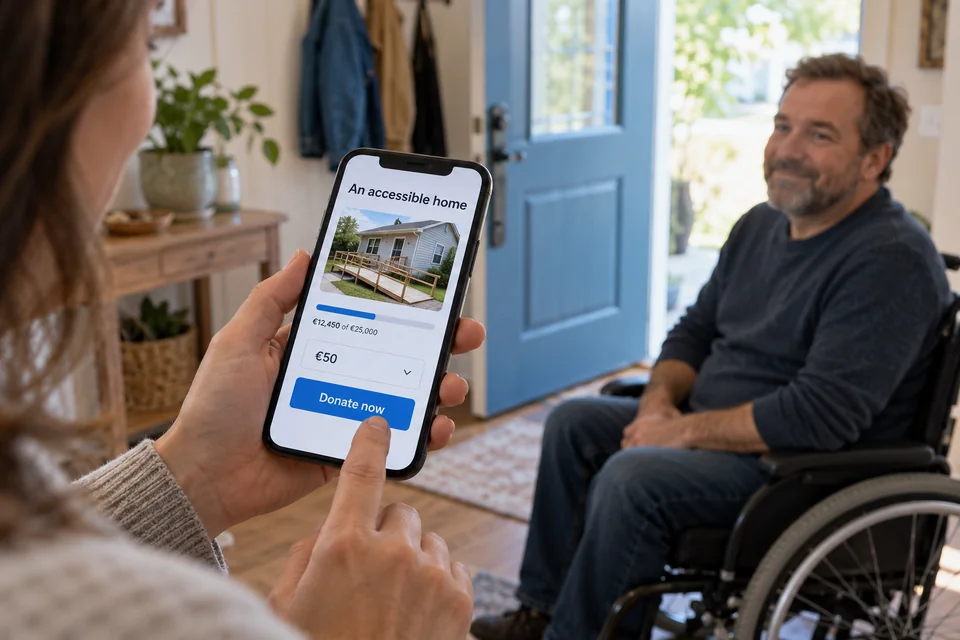
What personal fundraising is and who uses it
Personal fundraising is the practice of collecting small gifts from many people for one named individual or household. The organiser writes a short account of the situation, sets a target, and shares a link. Each donor gives freely and expects nothing back, not even a receipt for tax purposes in most cases.
People turn to a personal fundraiser when ordinary resources fall short and the need is clear: adapting a home for a family member who uses a wheelchair, covering funeral costs, replacing belongings after a fire, or bridging a period without income after an accident. What these cases share is a sudden or specific cost that friends can understand at once.
The organiser and the beneficiary are not always the same person. A sister, a neighbour or a colleague often sets up the appeal on someone else's behalf, which is why transparency about who receives the money matters so much.
Choosing between a personal fundraiser and a charity appeal
A personal appeal and a charity appeal look alike on screen but work differently. A registered charity is supervised by a regulator, publishes accounts and may offer tax relief to those who give. An individual raising money for personal needs usually has none of those features, and donors have to rely on trust.
Some situations are better handled through an existing charity or fund. If a recognised organisation already supports people with a particular illness or disability, it may pay for equipment directly, which spares the family the practical and legal questions that come with handling cash.
A personal route makes sense when no suitable organisation exists, when the need is highly specific, or when the family wants to keep control over how the money is used. It is wise to decide this early, because switching after a page has started attracting gifts causes confusion.
Telling the story without overselling it
The opening paragraph should say who needs help, what has happened and what the money is for, in plain sentences. Donors read quickly on a phone, often after a message from a friend, so the essentials must come before the background.
A good personal fundraiser is honest about what is known and what is not. If a treatment plan or a building quote is uncertain, say so. Exaggeration may raise more at first but erodes trust once relatives or colleagues compare the story with what they see.
- Name the person, the need and the date by which the money matters.
- Explain what will be bought or paid for, ideally with a quote or invoice in hand.
- Ask for consent from the person concerned before sharing private details or photographs.
Privacy deserves respect. Details about health, children or finances can stay online for years, so the organiser should include only what is needed to explain the request.
Setting a target and a timeline
A target should be tied to a real cost. Writing down the price of a ramp, a stairlift or a rental deposit, supported by a written estimate, makes the number credible. An unexplained round figure invites questions that the organiser may not enjoy answering.
Many platforms allow a campaign to keep whatever is collected even if the goal is missed, while others return money when a goal is not reached. Which model applies depends on the platform, so read its terms before launching individual fundraising and tell donors what will happen to any surplus or shortfall.
A realistic timeline helps as well. Appeals tend to gather most attention in the first days, when the organiser's own circle is paying attention, and again whenever a clear update appears. Planning two or three short updates in advance prevents a campaign from fading in silence.
Sharing an individual fundraising appeal responsibly
Individual fundraising spreads through people, not advertising. The first supporters are usually family and close friends, and their gifts and comments give later visitors a reason to feel at ease. Sending a personal message to each early supporter works better than posting the link once and hoping.
Local connections can widen the circle: a sports club, a workplace, a school parent group or a faith community may share an appeal with its members. Each should be asked politely and given a short summary it can pass on without changing the facts.
Pressure should be avoided. Repeated requests to the same people, or private messages to acquaintances who have not asked to be involved, damage relationships that a family may need long after the money has been spent.
Benefits, tax and other official matters
Supporters of a personal fundraiser usually cannot deduct their gifts, since tax relief tends to be tied to registered charities rather than to individuals. The position of the person receiving the money is a different matter. Some countries do not treat public gifts as income, whereas elsewhere particular circumstances can alter the treatment.
Recipients who receive means-tested support should be careful. In some systems, money that sits in a bank account can be counted when eligibility is assessed, so a large fundraiser could reduce or interrupt a benefit. The agency that pays the benefit, such as the Department for Work and Pensions in the United Kingdom or the Social Security Administration in the United States, can say how it treats gifts.
Because rules differ between countries and change over time, speaking to a benefits adviser or an accountant before the appeal begins is a sensible precaution. It costs little compared with the difficulty of repaying support that was paid in error.
Recognising a fake personal fundraiser
Fraudulent appeals for fundraising for personal needs often borrow real tragedies. Warning signs include a story with no named location, photographs that appear elsewhere on the internet, a beneficiary who cannot be reached, and pressure to pay outside the platform by transfer or voucher.
Donors can check whether the organiser is connected to the family through mutual friends, whether the local press or a community group has mentioned the case, and whether the platform shows that the beneficiary has been verified. A genuine organiser will not mind a donor asking how the money reaches the person in need.
If something looks wrong, report the page to the platform, which can freeze payouts, and tell the payment provider if money has already been sent. National consumer or fraud reporting services also collect these reports.
After the appeal: keeping faith with donors
Once the target is reached, a final message should thank donors and describe what the money achieved. If the adapted bathroom is finished or the repairs are done, a photograph with the beneficiary's permission lets supporters see the result of their kindness.
Any money left over needs an honest plan. Some organisers return it, some pass it to a related charity, and some explain that the surplus will go towards further costs of the same need. Whatever the choice, it should be stated openly and not discovered by accident.
Keeping simple records of what came in and what was spent protects the organiser of any personal fundraising campaign if anyone asks questions later, and it makes any conversation with a tax authority or benefits agency far easier.
Frequently asked questions
Is personal fundraising the same as raising money for a charity?
No. In personal fundraising the money goes to an individual or a household, with no charity supervising it. Charity appeals usually involve a registered organisation, published accounts and sometimes tax relief for donors, which personal appeals normally lack.
Do donors get a tax deduction?
Mostly no. Tax relief on giving usually belongs to registered charities, so money sent to an individual rarely qualifies. Rules differ from one country to the next, and a donor who needs certainty can put the question to their tax office.
Can donations affect benefits?
Possibly. Some means-tested schemes take account of savings or income when deciding who is eligible, and money received from supporters could fall within that. Whoever plans an appeal should first contact their benefits office and ask how public gifts are handled.
What if more money arrives than needed?
The organiser should decide and announce a plan before the surplus appears: returning it, passing it to a related charity, or using it for further costs of the same need. Clear wording from the start avoids disputes and protects trust.